
One of the most overused terms in real estate is “value-add.” Whether you are constructing a new ground-up development or acquiring an existing property, there is nearly always an opportunity to enhance its value and generate or increase revenue. The crucial factor lies in having experienced professionals who can effectively execute this strategy. In this article, we will delve into how skilled owners accomplish value-add.
How does a value-add merchant strategy differ from a long-term core fund?
The traditional approach to real estate investment involves acquiring existing properties or building new developments to hold long-term. Many sophisticated investors prefer this patient approach with a focus on long-term returns. However, another investment strategy has gained popularity among many investors, which revolves around the merchant strategy or value-add creation.
Typically, publicly-traded REITs do not offer this type of investment opportunity. Instead, private real estate funds and syndicators are the ones that specialize in the merchant strategy, involved in activities such as “re-purposing and selling” or “building and selling” properties. In this context, the Nicola Wealth Real Estate (NWRE) team launched the Nicola Value Add Real Estate Limited Partnership (NVARELP) in 2014 to cater specifically to this demand.
How is a value-add fund measured for performance?
In our experience, the life cycle for a typical value-add project is 24-36 months, provided everything goes according to plan. However, specific projects may face delays beyond an owner’s control, leading to longer timelines. To gauge the performance of such projects, the Internal Rate of Return (IRR) is the primary metric used. IRR is a time-weighted and disciplined approach that evaluates the return on capital. Nevertheless, there are some instances where IRR can be misleading. For example, if a project concludes much earlier than projected, it can result in an overestimation of the overall outcome.
To provide a more comprehensive assessment, the “equity multiple” measurement serves as a helpful check and balance on the project’s performance. This metric calculates the return on equity by multiplying the original capital invested without considering the time factor.
Over the past nine years, the NVARELP has matured and currently includes anywhere from 75 to 80 projects, all at different stages of completion. NVARELP aims to achieve a 13-15% IRR, net of all costs and fees to the investor. Additionally, it seeks to achieve a 1.5-2.0 equity multiple on each deal.
Since its inception (November 30, 2014), the historical performance of NVARELP stands at 14.2% as of May 31, 2023. Based on our market research, finding an open-ended, evergreen, value-add merchant fund featuring a diversified range of asset types in key markets to help minimize the risk seems to be an uncommon event in Canada.


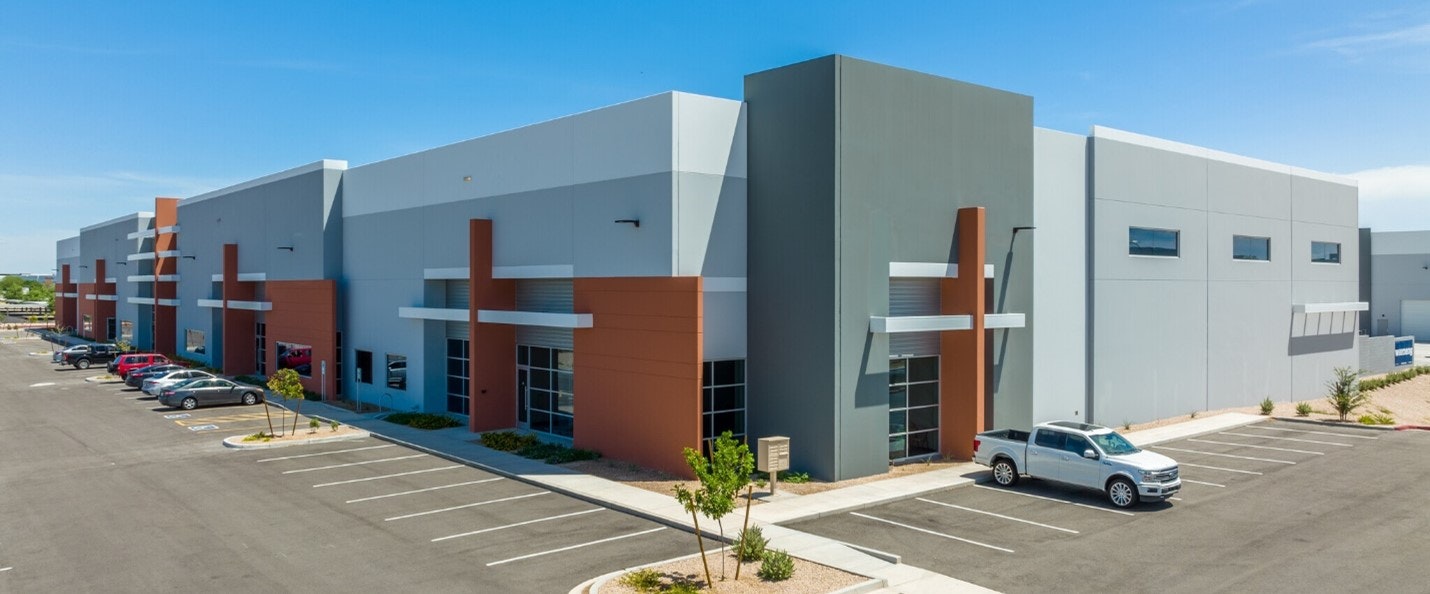
Industrial: South Valley Business Park – Phoenix, A.Z.
What are the biggest challenges with a value-add fund?
The primary benchmark for evaluating project performance is the Internal Rate of Return (IRR). However, the biggest challenge that adversely affects project outcomes is "time." Time exerts significant pressure on overall performance, and various aspects of a project can be affected by it. These include delays in municipal approvals, fluctuating interest rates, labour availability, material accessibility, leasing challenges, and asset disposition upon project completion.
The NWRE team employs a rigorous underwriting process for each asset, meticulously examining risk and performance. Through our experience, we have observed a consistent pattern: projects rarely adhere precisely to the original underwriting; they either outperform or underperform expectations. This observation highlights the importance of having a diversified pool of assets. Conducting sensitivity analysis during the underwriting stage becomes critical in showing which of the many variables is the most sensitive and has the most significant impact.


Life Sciences/Industrial: Evolution Block – Vancouver, B.C.
What type of investments are best performing in a value-add fund?
There are many benefits to having a well-diversified portfolio of value-add projects. Having multiple investment strategies in numerous markets helps provide a well-balanced approach. Among the popular investment themes are multi-family rental apartment buildings, residential condos, land entitlement, industrial for lease, small bay industrial condos, creative offices, and portfolio acquisitions (and sell-in pieces), to name a few. NVARELP focuses on these strategies in specific high-performing target markets.
It's important to note that while these strategies have the potential for significant success, outcomes can vary from market to market. For example, one of our favoured approaches is investing in industrial condominiums, also known as industrial strata. Some accomplished developers have achieved excellent results by building 10,000 to 15,000-square-foot unit sizes to meet the demand of owners/users who struggle to find existing standalone buildings of this size. Conversely, the NWRE team has chosen to address the need of smaller users seeking 2,500 to 4,000 square feet units. This size range appeals to owners/users aiming to own their facility and investors looking to lease to tenants as a long-term investment.
Vancouver and Toronto have emerged as the North American leaders for this product type. These cities cater to industrial users and investors in an environment where the vacancy rate for these projects hovers around 1.0%. The success of the industrial condo strategy in recent years has undeniably contributed to higher land costs in these markets.


Strata Industrial: IntraUrban Laurel – Vancouver, B.C.
When considering a joint venture, how important is partner selection?
There are many talented developers who are skilled at value-add projects for specific asset classes within particular markets. However, they frequently require a substantial capital partner to help with equity and debt requirements. The synergy between a skilled developer and a well-capitalized equity partner, who is real estate savvy, can make for a great partnership. NWRE has filled the role of a well-capitalized financial partner for several reputable developers, resulting in noteworthy achievements.
Collaborating with a seasoned local developer offers many advantages. These developers excel in critical facets such as site selection, project entitlement, efficient development and construction processes, and, ultimately, the strategic disposition of the asset. Typically, developers seek a strong capital partner capable of providing financial stability through equity and debt provisions. This support enables developers to focus on the project’s realization.
How does financing impact value add projects?
The rapid rise in interest rates, which began in March 2022, has introduced significant challenges in underwriting developments that aim in targeting returns within the 14-18% range and achieving an equity multiple ranging from 1.50 to 2.0X. In a low-interest rate environment, these metrics are more likely to be attainable. However, given the current higher interest rate situation, adjustments need to be made to render projects financially viable.
Higher interest rates are exerting strain on project proformas, and lenders are also tightening parameters as they gravitate toward more dependable borrowers. This is why having a strong capital partner is paramount for local developers operating within this evolving framework. On the flip side, higher interest rates can positively impact other aspects. For instance, land sellers held the upper hand in a lower interest rate environment, commanding premium pricing and favourable terms during transactions. Fast forward to the current environment, elevated interest rates have narrowed the pool of active participants willing to acquire land. As a result, land sellers find themselves compelled to be more flexible on pricing and terms relating to time.


Creative Office: Nickel Building & Fifth+Columbia – Vancouver, B.C.
When is the right time to de-risk a project?
Knowing when to optimize your profits is critical. The financing decisions often determine the need for pre-sales or leasing at specific stages to meet particular thresholds for loan installments. As the project’s risk decreases, more favourable terms can be obtained from a lender.
Initiating early marketing efforts is crucial for market testing and supporting your underwriting processes. Pre-sales or pre-leasing also serve to validate the market for the product and provide a foundation for determining pricing strategies. This can also pave the way for leveraging early pre-sales or pre-leasing during the marketing campaign.
However, it’s important to note that this strategy might not apply to all asset types. Take, for example, multi-family apartment buildings, which are generally seen as a more secure asset class due to housing supply challenges in Canada, resulting in notably low-interest rates. Many lenders recognize this aspect, often concurring that lease-up is likely to occur after the completion of construction and the issuance of occupancy permits.
NVARELP has over 80 projects, totalling over $1.0B in equity. The fund’s strength lies in its well-diversified asset types, market selections, and developer partnerships. Unlike investing in individual value-add projects, which typically are higher risk and are tied to a single project with no liquidity until completion, the open-ended value-add fund offers a more advantageous option. Its diversity brings about exposure to an array of assets and markets, coupled with the unique advantage of liquidity—something not commonly found within the Canadian market.
The Nicola Wealth Real Estate (NWRE) team is headquartered in Vancouver and is comprised of an experienced & diversified team of 65 specialists with a broad range of experience in different sectors of real estate. The NWRE team manages the three open-ended evergreen real estate limited partnerships for Nicola Wealth and their clients. The funds include the Nicola Canadian Real Estate Limited Partnership (NCRE LP), Nicola U.S. Real Estate Limited Partnership (NUSRE LP) and the Nicola Value Add Real Estate Limited Partnership (NVARE LP).
This material contains the current opinions of the author and such opinions are subject to change without notice. This material is distributed for informational purposes only. Forecasts, estimates, and certain information contained herein are based upon proprietary research and should not be considered as investment advice or a recommendation of any particular security, strategy or investment product. Information presented here has been obtained from sources believed to be reliable, but not guaranteed. All investments contain risk and may lose value. Please speak to your Nicola Wealth advisor for advice based on your unique circumstances. Returns are net of fund expenses, charged to date. Nicola Wealth Management Ltd. (Nicola Wealth) is registered as a Portfolio Manager, Exempt Market Dealer and Investment Fund Manager with the required securities commissions. This is not a sales solicitation. This investment is intended for tax residents of Canada who are accredited investors. Please read the relevant documentation for additional details and important disclosure information, including terms of redemption and limited liquidity. For a complete listing of Nicola Wealth Real Estate portfolios, please visit https://realestate.nicolawealth.com.


