
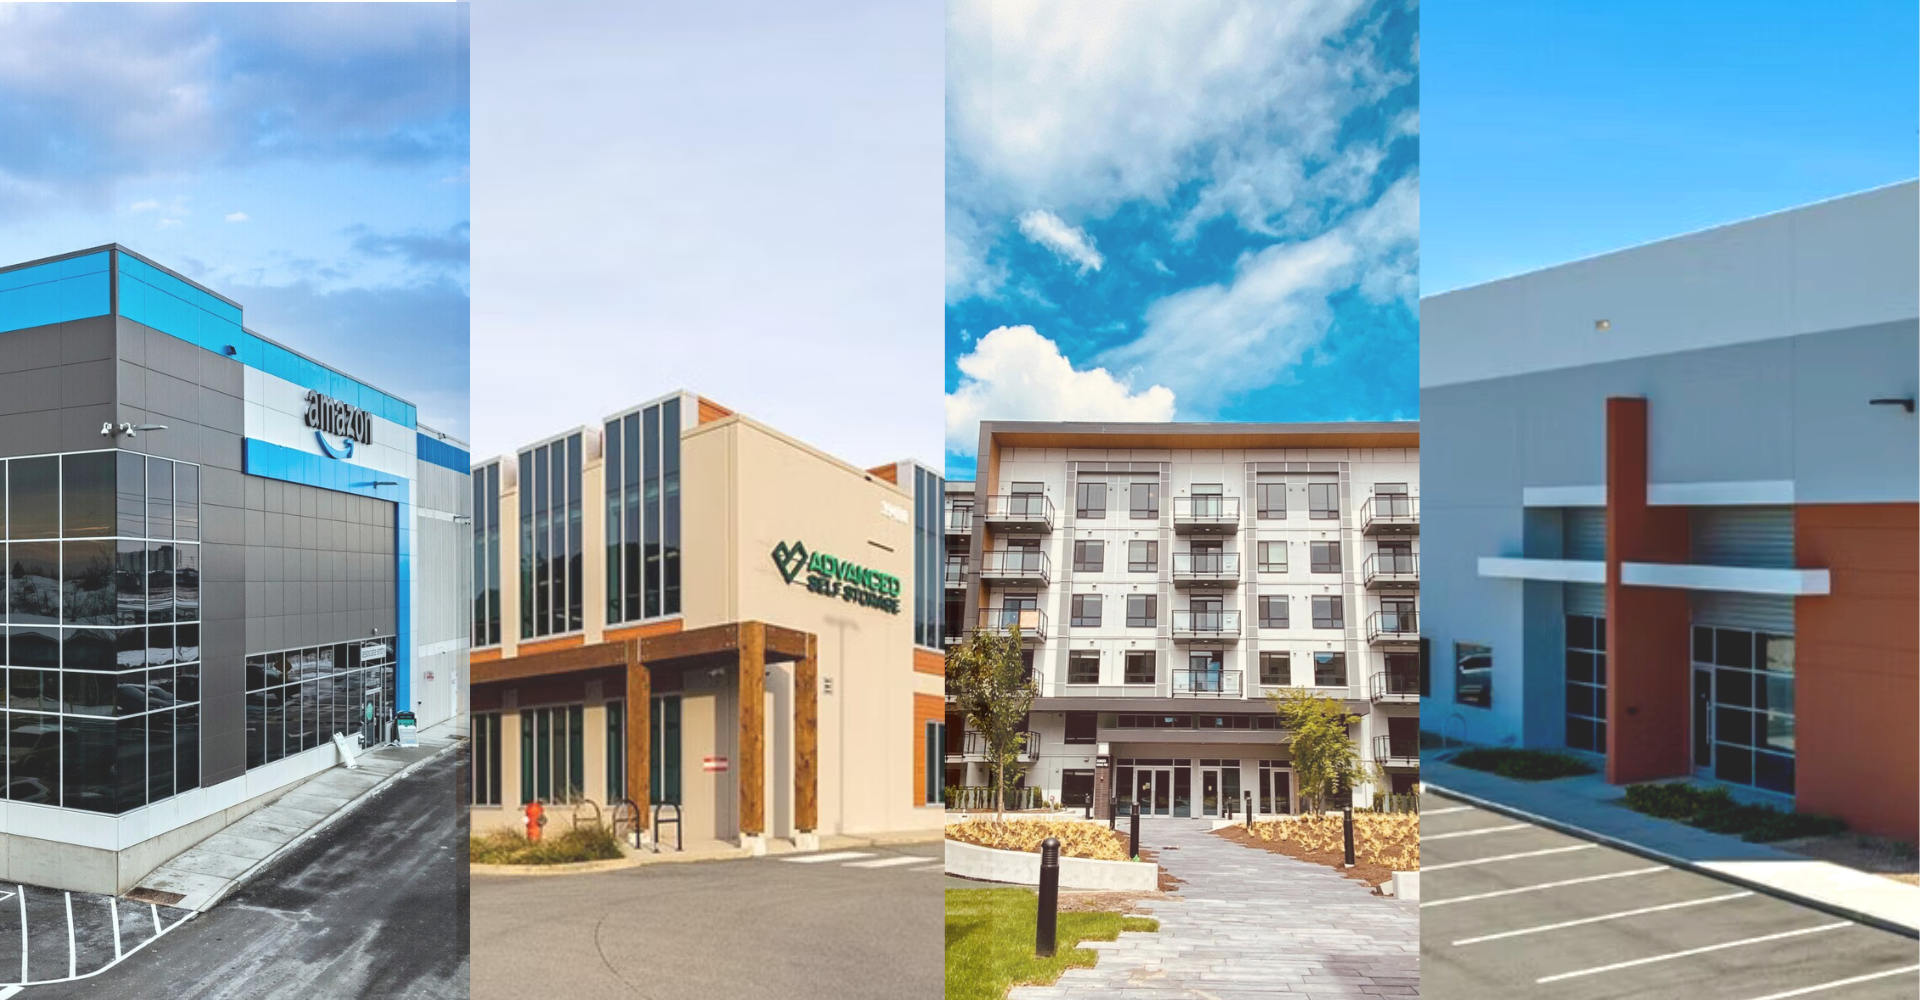
Part 1: Fund Composition Matters
The importance of fund composition in achieving strong risk-adjusted returns is a critical aspect of investing, and real estate is no exception.
Investors who choose to hold publicly traded stocks and bonds are usually aware that each of these asset classes has many sectors and attributes that impact both risk and return. In the case of stocks, for example, small-caps and emerging markets are expected to generate higher long-term returns but with notably higher volatility. Even within large-caps, the risk-return profile can vary between growth and value stocks.
Similar differences can be found in fixed income assets. High-yield bonds and distressed debt generally pay much higher interest than government or highly rated commercial bonds. Traditional mortgages on homes normally offer lower yields than mezzanine debt used in construction financing.
Within investment cycles, there are times when the returns generated from higher-risk assets are worth the added risk they present. However, there are also environments where the additional risk is too great and expected higher returns do not materialize. When creating any stock or fixed income portfolio, fund composition is essential. With regards to real estate, this has been especially true over the last few years.
Why is fund composition essential to overall performance?
In the words of Stephen Schwarzman, CEO and Founder of Blackstone Group, "You can't paint commercial real estate with one brush." In other words, not all real estate funds are created equally. His words resonate, especially in our current environment. In May 2020, shortly after the onset of COVID-19, we wrote an article titled “Real Estate’s Next Challenge – Fund Composition.” We stated that it was important to bulletproof your portfolio in preparation for the next economic event. That "next economic event" arrived much earlier than anticipated in the form of higher interest rates. The Nicola Wealth Real Estate (NWRE) team was fully prepared for this challenge.
The rising interest rate environment that has accrued since February 2022, with nine successive rate increases from the Bank of Canada, has put real estate in the spotlight. Debt is directly correlated with capitalization rates, and there is increased scrutiny on property valuations for private assets and funds. Fund composition can have a material impact on how property values are affected. Property valuations for the various asset classes are impacted based on several factors.
Firstly, market demand for leasing can be impacted by supply in any particular market. If a market has a low vacancy rate, there is a high probability of securing tenants at higher rental rates and with quick lease-up time. Another factor is the demand from investors to acquire specific assets that are impacted by the amount of capital required to maintain the assets. For example, high-rise office buildings typically command large tenant inducements and leasing fees, requiring large capital outlays. This can have a negative effect on the property value compared to asset types that are less capital intensive, making those investments more attractive and resulting in premium pricing. This is why fund composition matters, specifically market selection and asset types/allocation. Not to be overlooked are people. An experienced team with a hands-on approach can also determine outcomes.
In terms of market selection, too much exposure to one market could limit the upside and prove costly with limited liquidity if the economic drivers of that specific market deteriorate. Some fund managers purposely elect to focus on one specific market due to bench strength, fund size, or resources within the team. This can be beneficial when drivers for that market are strong but could also end up being punitive when those drivers deteriorate. Conversely, some fund managers feel it is essential to have a diversified strategy in markets to limit the downside. For example, the NWRE team completes a comprehensive analysis of each market we invest in to ensure strong demographics where we can succeed and employ our cluster strategy. Given the size of our portfolio, we have purposely elected to concentrate on selected major markets along with some strong secondary markets to provide a diversified and balanced approach. We aim for our target markets to possess features such as strong economic drivers for job growth, established universities, strong labour markets, a favourable tax environment, and low overall vacancy rates for the desired asset types.
Equally important is asset selection and allocation. In Q2 2020, at the onset of the pandemic, we witnessed firsthand how different assets performed during a stressed environment. This information reinforced that the NWRE team was on the right path with asset selection and allocation, as our real estate portfolios comprised strong-performing assets. The strongest performing assets within the Nicola Wealth real estate portfolios included multi-family rental apartments, small and mid-bay industrial, self-storage, industrial outside storage (IOS) sites, seniors living, flex industrial/office and single-story/low-rise office. These assets typically require low capital outlay both to retain existing tenants as well as attract new tenancies. We also favour these assets as they offer an attractive opportunity for rental growth, which is very important in this environment to help counterbalance any rise in cap rates.
The NWRE team has purposely steered away from high capital-intensive assets such as high-rise offices, certain types of retail, and hotels. This does not mean we will not consider these assets in the future, as we remain flexible and actively monitor trends. Fund composition is critical to building a well-diversified portfolio to ensure there is not too much exposure to one asset type and promotes a healthy balance of reliable and consistent cash flow. The NWRE team closely monitors market trends and performance for each asset type to make any necessary adjustments to limit overexposure to any one category. For example, the asset composition from 10 years ago for the Nicola Canadian Real Estate LP and the Nicola U.S. Real Estate LP, looks much different today and could very well look different again in 10 years' time should market conditions warrant further adjustments. We look for good deal velocity from leasing demand and acquisitions. The strong pace for both leasing and buyer demand reaffirms that cash flow is maintained, and values will hold firm for the quality assets.
How has this strategy translated into results?
When we look at the results over the previous year for the Nicola Canadian Real Estate Limited Partnership (NCRE LP), the biggest contributors to the 2022 returns were our industrial and self-storage assets. Our industrial assets, particularly in Toronto and the GTA, performed well despite rising cap rates due to the ongoing upward pressure on rental rates resulting in higher valuations. Yields for self-storage assets performed above expectation as the net income growth was significant due to our experienced in-house leasing and asset management teams moving rents to market after years of stagnant growth.


Industrial – Build to Own: 880 Avonhead Road, Mississauga, ON


Advanced Self Storage - Squamish
For the Nicola U.S. Real Estate Limited Partnership (NUSRE LP), the primary driver behind the double-digit returns for 2022 was the performance of our multi-family portfolio, which despite cap rate expansion, appreciated in value due to the level of net income growth. Our industrial distribution and flex assets also experienced similar rental growth contributing to the overall performance. The limited office assets we own in markets such as Denver, Houston, and Chicago did experience decreases in value, but they represent a very small allocation (less than 2%) within the NUSRE LP.


Multi-Family Rental – Build to Own: The Rex, 33689 King Road, Abbotsford, B.C.
The NWRE team reports to Morgan Stanley Capital International Inc. (MSCI) for portfolio benchmarking purposes for the NCRE LP and NUSRE LP. MSCI is a leading provider of global indices and benchmark-related products and services to investors worldwide. This is a measurement commonly used in the real estate sector to help benchmark at the asset level.
NCRE LP ranked 6th out of 47 funds (total return) in Q1 2023, reporting to the MSCI Canada Index (which excludes Super-Regional and Regional Shopping Centres).
NUSRE LP ranked 1st out of 38 funds (USD total return) in Q1 2023, reporting to the MSCI/PREA U.S. AFOE Quarterly Property Fund Index. PREA (Pension Real Estate Association) is a non-profit trade association for the global institutional real estate investment industry. AFOE (All Open-end Funds Property Level Index) applies to direct property only.
Interestingly, the NUSRE LP has ranked first in income growth in every quarter since March 2020, thanks in large part to our multi-family portfolio. In addition to the strength of the multi-family assets, we also outperformed the MSCI benchmark for industrial, retail, and other (development), only underperforming in the office sector.
Why do some investors prefer private real estate funds?
With publicly-traded REITs, investors may prefer liquidity, but they also knowingly sign up for volatility. Private real estate funds, however, typically attract patient, sophisticated investors who don’t require liquidity but subscribe to a long-term investment approach without volatility. The stability of reliable cash flow coupled with the opportunity for income growth stemming from a well-diversified portfolio is appealing to this type of investor. These features further underscore why fund composition matters. Cash flow certainly may vary depending on asset type and market selection. If done properly, each individual asset within the fund should have attractive liquidity if exposed to the market for disposition. The danger in disposing of prime assets is the challenge of replacing these properties at a future date at an attractive price.
Part 2: Property Valuations & Strategic Advantages
In Part 2 of this series, we delve into property valuations of private real estate investments, comparing the performance of Nicola Wealth Real Estate (NWRE) limited partnerships (LPs) with REITs and identifying areas of additional value. Additionally, we explore various strategies for real estate investors to position themselves in this dynamic environment. Lastly, we provide a brief outlook, outlining how the NWRE team plans to navigate the upcoming months.
Why are property valuations under the microscope?
Recently, there has been scrutiny of valuations for private real estate. This is understandable given that publicly traded REITs are trading well below their Net Asset Value (NAV). However, if you asked CEOs of REITs, most would agree that the REITs are not representative of the true market value. REITs are not prepared to sell their prime assets in this current environment just to achieve liquidity. The primary reason for this is they would be challenged to replace these prime assets in the future.
Lack of confidence in the public markets is caused by emotional behaviour that creates volatility. Rising interest rates play a significant role in market sentiment as some (but not all) of the REITs typically use floating debt which has caught many off-guard. This is not the case for NWRE LPs as most of our debt is locked in long-term at attractive rates.
The common question we are asked relates directly to our valuation process. It is important to note that the main industry players all use appraisers. NWRE, public REITs, pension funds, and institutional owners use professional appraisal firms and methodologies.
Every asset (excluding those under construction) in the Nicola Canadian Real Estate Limited Partnership (NCRE LP) and Nicola U.S. Real Estate Limited Partnership (NUSRE LP) is appraised on a quarterly basis. This process is utilized to help establish a Net Asset Value (NAV) every month to ensure fairness to our investors. This includes one full narrative report and three quarterly updates.
No internal valuations are completed for our income-producing properties. The third-party appraisals are reviewed by the NWRE team starting with the asset management and leasing teams who undertake a thorough analysis to ensure all assumptions, market comparables, and appraisal methodologies are correct. The independent third-party appraiser has the final say on valuation.
Value lies in the team behind the fund
Not only are real estate funds created differently, but so are the real estate teams that run their respective portfolios. This is where we believe the NWRE team has a big advantage. We believe the “noise” in the media about the “imminent demise of commercial real estate” is overstated. Peeling back the layers of these articles, one will find that the majority relates to downtown high-rise offices, an asset type that we do not hold in our portfolios. Hotels and enclosed malls have also received negative press, for obvious reasons coming out of the pandemic, neither of which we own.
We attribute the performance of our real estate limited partnerships to the strength of our in-house NWRE team comprised of 65+ people, with a wide range of expertise, actively managing the real estate LPs. Headquartered in Vancouver, the team includes the following areas of specialization: acquisitions/dispositions, active asset management, leasing, mortgage debt, the development team for build-to-core and finance/accounting.
Once a property is acquired or developed, the hard work begins, starting with active asset management. We employ a "hands-on" approach with a high level of collaboration across various departments to ensure the best possible outcome for each and every asset. This, in turn, aims to deliver strong performance for the funds and, ultimately, solid returns for the investors.
Selecting the right markets and asset types will go a long way in ensuring high occupancy levels are maintained. This lays the foundation for reliable cash flow and healthy annual income growth. Our focus is on achieving high occupancy rates, rental growth, and securing quality covenant tenants. Our team strategically works on leasing outcomes that can enhance the valuation and set the stage for the debt team to refinance the asset on improved terms in the future.
Why is build-to-own a good strategy?
Build-to-own is a popular strategy for many sophisticated real estate groups in both publicly traded REITs and private real estate funds. If done properly, a build-to-own strategy can result in attractive development yields, and one can be rewarded for the risk. Selecting the right location and asset type positions the property for potential success for a timely lease-up and stabilization upon project completion.


Multi-Family Rental - Build to Own: The James, 345 Quebec Street, Victoria, B.C.
The NWRE team has an experienced in-house development team to execute this strategy and create value for our investors. Our team specializes in various types of developments, such as multi-family rental apartments, industrial distribution, self-storage, and creative office products. Focusing on new product development helps minimize capital expenditures in the foreseeable future and, more importantly, generates risk-adjusted leveraged returns for our investors.


Industrial - Build to Own: 601-607 Milner, Toronto, ON
Why is mortgage debt critical to fund performance?
One of the many challenges for publicly-traded REITs and certain private funds is their reliance on floating debt. Everyone was spoiled in the low-interest rate environment over the past 10 years. Using floating debt was a popular strategy used by many fund managers to help provide enhanced returns. However, many have been caught off guard in this rising interest rate environment which has led to negative impacts on returns and further distress from higher redemption requests.
The NWRE team has an experienced three-person in-house debt team that manages our entire $9.5B portfolio including acquisitions, construction, land loans, and takeout financing. This has led to some favourable outcomes for our LPs. The NWRE debt team adopted an aggressive approach in late 2021 to lock in debt and renew early on the anticipation of rising interest rates with the overall goal of de-risking our portfolios.
Both income portfolios boast low debt coverage ratio (NCRE LP @ 43% & NUSRE LP @ 48% as of June 2023) meaning that the LPs are not overleveraged. Moreover, our two income portfolios have minimal exposure to floating rate mortgages as a large portion of the portfolio is locked in at favourable rates (by today’s standards) for terms ranging from 5 to 10 years. NCRE LP has 71% fixed with only 29% floating. Whereas NUSRE LP has 91% fixed and 9% floating. Overall, there is minimal exposure to floating rate mortgages.
Why does governance provide good oversight and accountability?
Smaller fund managers/owners may not have proper oversight on decision-making, but governance is vital to provide proper belts and suspenders for the larger fund managers/owners where the stakes may be much higher. The NWRE team operates with a strong level of oversight starting with the NWRE Investment Committee that is comprised of four independent members, each having extensive real estate experience. Every acquisition and disposition must receive unanimous approval prior to proceeding which promotes healthy discussion and accountability. In addition to the Investment Committee, the NWRE team reports to the firm’s Investment Review Board, Board of Directors, and the Senior Leadership team. Overall, there is strong governance for the Nicola Wealth’s Real Estate LPs.
Where do we go from here?
Since February 2022, the Bank of Canada has raised the overnight lending rate nine times, increasing it from 0.25% to 4.75%. This rapid increase hasn't been witnessed since the early 1980s. In the early 2000s, the real estate markets benefited from access to relatively cheap money, abundant capital, and, most importantly, positive leverage of 200-300 basis points. However, these favourable conditions have now quickly disappeared, leading to differences in how lenders view various asset types and markets.
Challenging assets have seen significant declines in their valuations and, more worryingly, have become very difficult to finance. On the other hand, in-demand assets have experienced only moderate valuation impacts, but access to debt remains relatively strong. The main challenge now is that there is little to no positive leverage available in the current environment.
There is a flight to quality by lenders in terms of asset types, target markets, and borrowers. The overflowing market of capital experienced in 2021 and early 2022 has dissolved and is not expected to improve until 2024. In this stressed environment, there is also a flight to quality for investors on where to invest. Healthy and strong portfolios are well positioned to prosper in this challenging environment and can take advantage of those who may be forced to liquidate their quality assets.
In closing, we believe the NWRE team is in a strong position to benefit from this environment. We understand the importance of a well-diversified portfolio comprised of the desired assets in the preferred markets that have the prospect of maintaining and growing revenue. At this time, many players are on the sidelines reassessing their portfolios with high debt and redemption requests thereby creating a golden opportunity for funds such as the NWRE LPs which are well capitalized and designed for resiliency.
Part 3: Canada’s Rental Housing Supply Shortage
Most of us can agree that Canada is one of the best places in the world to live. We have a democratic society and a generally safe environment for our citizens to reside in harmony. Our vast geography and abundant natural resources make Canada the envy of the world. So, naturally, this relatively welcoming country attracts individuals and families from around the world who intend to make Canada home. The challenge is, where will they live? In this article, we will provide an overview of the contributing factors to Canada’s rental housing supply shortage.
Multi-Family Rental - The Rex Apartments, Abbotsford, B.C. | 207 Units – Completed in 2021
How did we get here?
In Q1 2020, shortly after the onset of COVID-19, Canada’s population was hovering around 38 million people. Since that time, Canada’s population has increased and has now surpassed 40 million people. While the increase in immigration is encouraging, it appears to have caught many of us, off guard. This figure does not take into account the growing number of international students enrolling in our universities at a record pace. With immigration continuing at a rate of 1.0 million new residents per year, the pressing question arises: How can we ensure an adequate supply of housing for everyone?
How can Canadians afford housing?
Since March 2022, the Bank of Canada has increased interest rates ten consecutive times from 0.25% to 5.0%. Economic experts suggest more interest rate hikes are coming as the Bank of Canada is determined to bring inflation back down to 2.0% and maintain that level for a sustained period. While in the long term this may be seen as a prudent strategy, it is also translating to serious short-term pain for a lot of Canadians. If inflation can be tamed by Q4 2023 through to Q2 2024, then perhaps we can expect the Bank of Canada to start easing the interest rates to help stimulate the economy. However, we may never get back to the historic low interest rates experienced in February 2022 as access to cheap money contributed significantly to our current high inflationary environment. Dropping halfway may be a good compromise.
In the meantime, higher interest rates have all but eliminated the affordability for the average Canadian to realize their homeownership dream unless they get financial aid from a third party, often family. The higher interest rates also present challenges for developers of condominiums and single-family homes to build and sell their products to the end consumer at affordable pricing. Rising interest rates have also applied more pressure to the already undersupplied rental stock. Whether it is home ownership or rental accommodation, Canada has a serious problem.
How does new supply help affordability?
The vacancy rate for multi-family rental apartment product is consistently low, typically in the single-digit range. This shortage of available rental properties is a supply issue that affects the housing market. Higher rents not only impact individuals’ housing costs but also contribute to overall inflation, consequently affecting factors such as job wages and consumer goods prices. In cities like Toronto and Vancouver, the vacancy rate is even lower than single digits, often below 1.0%, and has remained so for an extended period. It is common for landlords and owners to be blamed for charging high rents, but it’s important to note that rent control policies typically limit increases to around 2.0% and often fail to keep pace with the rising costs of property taxes, insurance, and building repairs/upgrades. Increasing the supply of new rental units would alleviate the pressure on rents for consumers. Unfortunately, many developers and apartment owners face significant obstacles, such as the speed of bringing new units to market and the high costs involved, which hinder their ability to provide additional rental housing options. Consequently, we feel that current government policies discourage developers from constructing new rental properties.
How can our government help?
Federal, provincial, and municipal governments express their desire to address the issue of housing supply, but their proposed solutions often involve more taxes and fragmented approaches. It is crucial for all three levels of government to collaborate and work together to resolve the housing crisis.
Each government has a vital role to play in finding solutions. Here are some recommended measures that we feel can help stimulate the rental housing supply:


Multi-Family Rental - Spencer Block, Victoria, B.C. | 278 Units – Under Construction
On a federal level:
- Eliminate GST on new rental apartment buildings payable by developers and on new condominiums for home purchasers. Developers are already paying GST on the materials that go into building these structures. We feel this can be a significant cost in both scenarios and deteriorates affordability.
- Allow 10-year GST deferrals which would provide rental housing developers the opportunity to pay GST over time with stabilized rental income. This can reduce financeable project costs and requirements in the capital stack.
- Provide low interest rate construction loans in the 1-2% range to encourage developers of multi-family rental apartment buildings and condominiums, supplying the market with new housing options.
- Ease the Prohibition on the Purchase of Residential Property by Non-Canadians Act which is negatively impacting developers who have traditionally relied on this buyer group to support new condominium towers.
- Provide improved financing options not only for first-time buyers but also for citizens below a certain income level.
- Ease the mortgage stress test so that more people can afford their first home purchase.
- CMHC could expand upon and enhance its RCFI and MLI Select rental construction financing program to encourage more rental housing construction to proceed.
- Help provide funding to hire more staff at CMHC (more on that below).
On a provincial level:
- Reduce the property purchase tax which can be a heavy burden on citizens with limited budgets, particularly first-time buyers.
- Assist municipalities in offering a 10-year "property tax holiday" for new multi-family rental apartment buildings. We feel this will reduce overall costs and enable reduced rents for tenants.
- Help municipalities cover overhead costs to staff up planning departments and expedite the approval process.
- Hold municipalities accountable for delayed processing. We feel there should be a cap on timing for approvals and permits which creates predictability.
- Provide funding to developers who build for 100% low-cost non-market housing.
Multi-Family Rental - The James at Harbour Towers, Victoria, B.C. | 219 Units – Completed in 2020
On a municipal level:
- Create and adhere to predictable processing times for approvals and permits. Eliminate any potential red tape and improve the speed to market. Based on our experience, the rezoning process alone can take as much as 24-36 months which puts a heavy burden on developers for holding costs. Elongated project schedules also erode affordability.
- Reduce development cost levies to help improve project costs for developers. Extend payment deadlines for the development levies to the end of the project once stabilized and ready for occupancy permit.
- Provide a 10-year property tax holiday for all new multi-family rental apartment projects to encourage developers and apartment owners to provide new supply.
- Eliminate or significantly reduce the empty homes tax.
- Waive the rezoning public hearing process, at the advice of the planning department, for projects that adhere to city policies. Projects that do not challenge policy should be expedited. This would reduce processing time.
- Compress and expedite projects that deliver significant affordable housing, rental housing, and job space.
- Significantly reduce or remove Development Cost Levies for rental housing charged by municipal governments.
How does CMHC play a role in solving the housing shortage?
The Canada Mortgage and Housing Corporation (CMHC), established by the federal government, serves a critical role in providing insurance to lenders for developers seeking construction and term financing. However, CMHC is currently experiencing delays in processing loan applications. This delay has resulted in our team witnessing a backlog of approximately five to six months, with no signs of relief in sight. Prompt and effective action is necessary for the federal government to address this issue.


Multi-Family Rental - Meridian, Coquitlam, B.C. (Partner: Townline) | 267 Units – Under Construction
What is the impact if we could bring all three levels of government together?
In our opinion, there are several potential benefits that could result from addressing the housing supply shortage and making housing more affordable. While these points are subjective, they present potential positive outcomes:
- It would take pressure off inflation as increased housing supply would surely bring costs under control making housing more affordable for consumers whether renters or home-owners.
- Collaboration at all government levels would generate more jobs and spur more education and training for trades schools, colleges, and universities.
- Developers would have more incentive to deliver new supply at affordable cost in a timely manner.
If all levels of government can work together, we can truly make Canada not only a great place to live and work but also an affordable one. It will also help make the Canadian dream of home ownership achievable.
The multi-family rental apartment building asset class is considered by most sophisticated investors as the preferred asset class. It is viewed as a safe investment with minimal vacancy risk notwithstanding the low rental growth constraints caused by rent control.
Our federal government recently elected to spend up to$15.0 billion to Stellantis in production incentives to save the electric vehicle plant in Windsor, Ontario. This funding move was on the heels of the federal government and Ontario promising up to $13.0 billion to Volkswagen in production subsidies for every battery the company makes and sells.
If you were to apply this combined $28.0 billion granted to these foreign multinational companies and applied an average cost of $300,000 to build a new apartment unit in Canada, these same funds would generate over 93,000 new apartment units. We believe that providing affordable housing supply is equally as important as job creation.
We recognize that many of the suggestions listed above could be viewed as “lost revenue” and/or unpopular.
Our Nicola Wealth Real Estate team has been active in building new multi-family rental apartment product in British Columbia. A few examples of completed projects and projects currently under construction include:
- The Rex Apartments – Abbotsford, B.C.
- Spencer Block – Victoria, B.C.
- The James at Harbour Towers – Victoria, B.C.
- The Meridian – Coquitlam, B.C.
These projects are adding to the new supply that is needed in our province. Our team has several other projects in the queue that will contribute additional supply, but the costs are much higher and taking longer.
Part 4: The Merits of a Value-Add Fund
One of the most overused terms in real estate is “value-add.” Whether you are constructing a new ground-up development or acquiring an existing property, there is nearly always an opportunity to enhance its value and generate or increase revenue. The crucial factor lies in having experienced professionals who can effectively execute this strategy. In this article, we will delve into how skilled owners accomplish value-add.
How does a value-add merchant strategy differ from a long-term core fund?
The traditional approach to real estate investment involves acquiring existing properties or building new developments to hold long-term. Many sophisticated investors prefer this patient approach with a focus on long-term returns. However, another investment strategy has gained popularity among many investors, which revolves around the merchant strategy or value-add creation.
Typically, publicly-traded REITs do not offer this type of investment opportunity. Instead, private real estate funds and syndicators are the ones that specialize in the merchant strategy, involved in activities such as “re-purposing and selling” or “building and selling” properties. In this context, the Nicola Wealth Real Estate (NWRE) team launched the Nicola Value Add Real Estate Limited Partnership (NVARELP) in 2014 to cater specifically to this demand.
How is a value-add fund measured for performance?
In our experience, the life cycle for a typical value-add project is 24-36 months, provided everything goes according to plan. However, specific projects may face delays beyond an owner’s control, leading to longer timelines. To gauge the performance of such projects, the Internal Rate of Return (IRR) is the primary metric used. IRR is a time-weighted and disciplined approach that evaluates the return on capital. Nevertheless, there are some instances where IRR can be misleading. For example, if a project concludes much earlier than projected, it can result in an overestimation of the overall outcome.
To provide a more comprehensive assessment, the “equity multiple” measurement serves as a helpful check and balance on the project’s performance. This metric calculates the return on equity by multiplying the original capital invested without considering the time factor.
Over the past nine years, the NVARELP has matured and currently includes anywhere from 75 to 80 projects, all at different stages of completion. NVARELP aims to achieve a 13-15% IRR, net of all costs and fees to the investor. Additionally, it seeks to achieve a 1.5-2.0 equity multiple on each deal.
Since its inception (November 30, 2014), the historical performance of NVARELP stands at 14.2% as of May 31, 2023. Based on our market research, finding an open-ended, evergreen, value-add merchant fund featuring a diversified range of asset types in key markets to help minimize the risk seems to be an uncommon event in Canada.


Industrial: South Valley Business Park – Phoenix, A.Z.
What are the biggest challenges with a value-add fund?
The primary benchmark for evaluating project performance is the Internal Rate of Return (IRR). However, the biggest challenge that adversely affects project outcomes is "time." Time exerts significant pressure on overall performance, and various aspects of a project can be affected by it. These include delays in municipal approvals, fluctuating interest rates, labour availability, material accessibility, leasing challenges, and asset disposition upon project completion.
The NWRE team employs a rigorous underwriting process for each asset, meticulously examining risk and performance. Through our experience, we have observed a consistent pattern: projects rarely adhere precisely to the original underwriting; they either outperform or underperform expectations. This observation highlights the importance of having a diversified pool of assets. Conducting sensitivity analysis during the underwriting stage becomes critical in showing which of the many variables is the most sensitive and has the most significant impact.


Life Sciences/Industrial: Evolution Block – Vancouver, B.C.
What type of investments are best performing in a value-add fund?
There are many benefits to having a well-diversified portfolio of value-add projects. Having multiple investment strategies in numerous markets helps provide a well-balanced approach. Among the popular investment themes are multi-family rental apartment buildings, residential condos, land entitlement, industrial for lease, small bay industrial condos, creative offices, and portfolio acquisitions (and sell-in pieces), to name a few. NVARELP focuses on these strategies in specific high-performing target markets.
It's important to note that while these strategies have the potential for significant success, outcomes can vary from market to market. For example, one of our favoured approaches is investing in industrial condominiums, also known as industrial strata. Some accomplished developers have achieved excellent results by building 10,000 to 15,000-square-foot unit sizes to meet the demand of owners/users who struggle to find existing standalone buildings of this size. Conversely, the NWRE team has chosen to address the need of smaller users seeking 2,500 to 4,000 square feet units. This size range appeals to owners/users aiming to own their facility and investors looking to lease to tenants as a long-term investment.
Vancouver and Toronto have emerged as the North American leaders for this product type. These cities cater to industrial users and investors in an environment where the vacancy rate for these projects hovers around 1.0%. The success of the industrial condo strategy in recent years has undeniably contributed to higher land costs in these markets.


Strata Industrial: IntraUrban Laurel – Vancouver, B.C.
When considering a joint venture, how important is partner selection?
There are many talented developers who are skilled at value-add projects for specific asset classes within particular markets. However, they frequently require a substantial capital partner to help with equity and debt requirements. The synergy between a skilled developer and a well-capitalized equity partner, who is real estate savvy, can make for a great partnership. NWRE has filled the role of a well-capitalized financial partner for several reputable developers, resulting in noteworthy achievements.
Collaborating with a seasoned local developer offers many advantages. These developers excel in critical facets such as site selection, project entitlement, efficient development and construction processes, and, ultimately, the strategic disposition of the asset. Typically, developers seek a strong capital partner capable of providing financial stability through equity and debt provisions. This support enables developers to focus on the project’s realization.
How does financing impact value add projects?
The rapid rise in interest rates, which began in March 2022, has introduced significant challenges in underwriting developments that aim in targeting returns within the 14-18% range and achieving an equity multiple ranging from 1.50 to 2.0X. In a low-interest rate environment, these metrics are more likely to be attainable. However, given the current higher interest rate situation, adjustments need to be made to render projects financially viable.
Higher interest rates are exerting strain on project proformas, and lenders are also tightening parameters as they gravitate toward more dependable borrowers. This is why having a strong capital partner is paramount for local developers operating within this evolving framework. On the flip side, higher interest rates can positively impact other aspects. For instance, land sellers held the upper hand in a lower interest rate environment, commanding premium pricing and favourable terms during transactions. Fast forward to the current environment, elevated interest rates have narrowed the pool of active participants willing to acquire land. As a result, land sellers find themselves compelled to be more flexible on pricing and terms relating to time.


Creative Office: Nickel Building & Fifth+Columbia – Vancouver, B.C.
When is the right time to de-risk a project?
Knowing when to optimize your profits is critical. The financing decisions often determine the need for pre-sales or leasing at specific stages to meet particular thresholds for loan installments. As the project’s risk decreases, more favourable terms can be obtained from a lender.
Initiating early marketing efforts is crucial for market testing and supporting your underwriting processes. Pre-sales or pre-leasing also serve to validate the market for the product and provide a foundation for determining pricing strategies. This can also pave the way for leveraging early pre-sales or pre-leasing during the marketing campaign.
However, it’s important to note that this strategy might not apply to all asset types. Take, for example, multi-family apartment buildings, which are generally seen as a more secure asset class due to housing supply challenges in Canada, resulting in notably low-interest rates. Many lenders recognize this aspect, often concurring that lease-up is likely to occur after the completion of construction and the issuance of occupancy permits.
NVARELP has over 80 projects, totalling over $1.0B in equity. The fund’s strength lies in its well-diversified asset types, market selections, and developer partnerships. Unlike investing in individual value-add projects, which typically are higher risk and are tied to a single project with no liquidity until completion, the open-ended value-add fund offers a more advantageous option. Its diversity brings about exposure to an array of assets and markets, coupled with the unique advantage of liquidity—something not commonly found within the Canadian market.
The Nicola Wealth Real Estate (NWRE) team is headquartered in Vancouver and is comprised of an experienced & diversified team of 65 specialists with a broad range of experience in different sectors of real estate. The NWRE team manages the three open-ended evergreen real estate limited partnerships for Nicola Wealth and their clients. The funds include the Nicola Canadian Real Estate Limited Partnership (NCRE LP), Nicola U.S. Real Estate Limited Partnership (NUSRE LP) and the Nicola Value Add Real Estate Limited Partnership (NVARE LP).
This material contains the current opinions of the author and such opinions are subject to change without notice. This material is distributed for informational purposes only. Forecasts, estimates, and certain information contained herein are based upon proprietary research and should not be considered as investment advice or a recommendation of any particular security, strategy or investment product. Information presented here has been obtained from sources believed to be reliable, but not guaranteed. All investments contain risk and may lose value. Please speak to your Nicola Wealth advisor for advice based on your unique circumstances. Nicola Wealth Management Ltd. (Nicola Wealth) is registered as a Portfolio Manager, Exempt Market Dealer and Investment Fund Manager with the required securities commissions. This is not a sales solicitation. This investment is intended for tax residents of Canada who are accredited investors. Please read the relevant documentation for additional details and important disclosure information, including terms of redemption and limited liquidity. For a complete listing of Nicola Wealth Real Estate portfolios, please visit https://realestate.nicolawealth.com.


